
25.9 Million Contracts Into One Friday (18 September 2026): Triple Witching Lands Between a Fed Hike and a BoJ Hike — and Gross Notional Is the Wrong Number
The quarterly expiry lands 18 September, two days after the Fed hiked and hours after the BoJ. What actually settles, and why the trillion-dollar headline misleads.
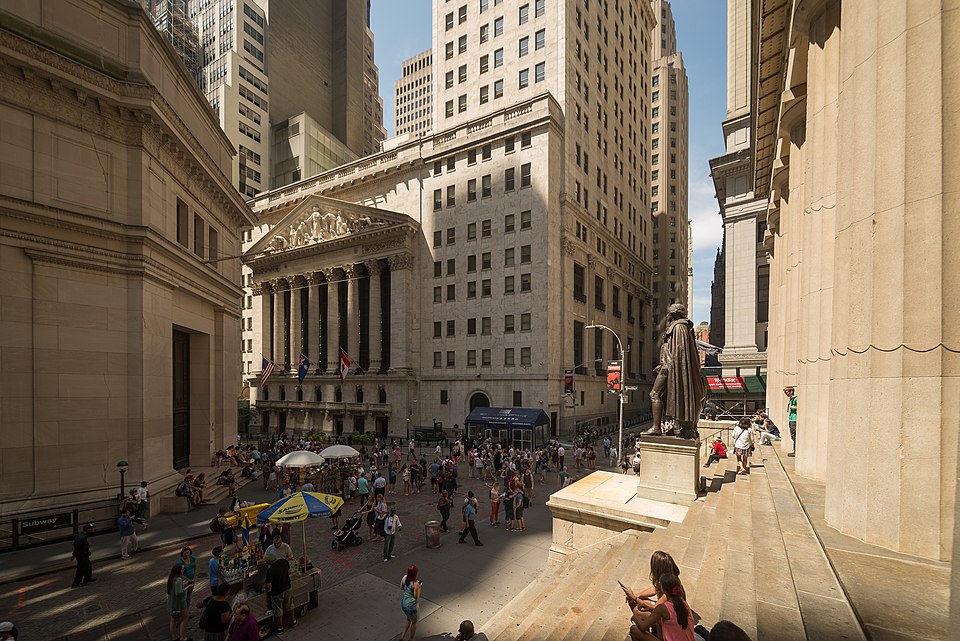
25.9 Million Contracts Into One Friday (18 September 2026): Triple Witching Lands Between a Fed Hike and a BoJ Hike — and Gross Notional Is the Wrong Number
Friday 18 September is the quarterly expiry, and it has been handed an unusually crowded week. The Federal Reserve raised rates on Wednesday for the first time since July 2023, on a 12–0 vote. The Bank of Japan raised its own policy rate to a 31-year high on Friday morning in Tokyo. And at Friday's close, index funds have to execute an S&P 500 membership change in the same auction as every P.M.-settled option outstanding. Estimates of the notional expiring run into the trillions, and the trillions are the least informative number available. Here is what actually settles, when, and through which channel it can touch a price.
- Three things expire together. Stock index futures, stock index options and single-stock options, on the third Friday of each quarter month — 18 September this time.
- The day settles twice, not once. Standard S&P 500 index options are A.M.-settled off Friday's opening prints; end-of-quarter and weekly index options, ETF options and every single-stock option settle at the close.
- The headline notional is a reference amount. Cboe reported 25,923,645 contracts of SPX open interest as at 17 September — roughly $19.7tn gross at a $100 multiplier, across all expirations. Nothing like that sum is at risk.
- Citadel Securities' research desk put about $6.2tn on the 18 September line in a note published 31 August, on data through late August, and said the figure would grow as nearer-dated positions rolled in. It is an estimate of paper outstanding, not of money.
- Notional carries no direction. A call and a put on the same strike both count. So does each leg of a spread.
- The real channel is dealer hedging. An expiry removes the hedging attached to expiring contracts — a damper lifted, not a push applied.
- The week's two rate decisions both landed as expected. The Fed to 3.75–4.00% on Wednesday; the BoJ to 1.25% on Friday, 7–2, with the yen weaker at 156.64 afterwards.
- A second mechanical order sits in the same closing auction. Bloom Energy, Everpure and Illumina join the S&P 500 before Monday's open, so the index trade prints Friday at the close.
- The rate decisions are the part that reaches currencies — see how the interest-rate factor is scoring the eight majors on the live meter.
What actually expires, and why there are three of them
"Triple witching" is a nickname the market gave to a scheduling coincidence. Four times a year — the third Friday of March, June, September and December — three separate families of contract reach expiration in the same session: futures on stock indices, options on stock indices, and options on individual stocks. Cboe's 2026 expiration calendar does not use the phrase at all. It marks the standard expiration, flags a separate last-trade date for A.M.-settled equity index options, and adds a third marker for end-of-quarter options, which it defines as expiring "at the close in Quarter Months (March, June, September and December)."
You will still see the day called quadruple witching. That fourth witch was single-stock futures, which no longer trade in the United States. The label outlived the product.
What makes the quarterly version larger than an ordinary monthly expiration is not that anything special happens to options. It is that the index futures come due at the same time. The September E-mini S&P 500 contract has to be closed, rolled into December, or carried into final settlement — and the bulk of that rolling happens in the preceding week, not on Friday. By the time the expiry itself arrives, a large share of the futures positioning that a headline attributes to the day has already moved to the next quarter.
The same Friday settles twice, six and a half hours apart
This is the mechanic most often skipped, and it changes what the session actually is.
The standard third-Friday S&P 500 index options are A.M.-settled. Their settlement value is not a price anyone trades; it is calculated from the opening prices of the index's component stocks on Friday morning. Because the 500 constituents do not all open at the same instant, that value is assembled out of the opening auction and has no obligation to equal any index level printed later in the day. For every holder of a standard SPX contract, the entire outcome is decided in the first minutes of the session.
Everything else waits. Cboe's SPX product page describes the contract as cash-settled and European-exercise with a choice of A.M. or P.M. expirations, and the P.M. side — the end-of-quarter contracts, the weeklies dated to that Friday, the ETF options and every single-stock option — settles against Friday's closing prices.
So an expiry Friday is two events with an ordinary trading day in between, and the opening auction is doing double duty as a settlement calculation. A write-up that treats the day as a single moment of released pressure is describing a market structure that does not exist.
The trillion-dollar number, and what it is not
Citadel Securities' Global Market Intelligence team, in a note published on 31 August by strategist Scott Rubner, put roughly $6.2 trillion of US options notional on the 18 September line, out of about $9.6 trillion scheduled to expire between that publication date and the quarterly expiry — with the caveat that the single-day figure would grow as nearer-dated positions rolled into it. That is an estimate published in late August, on data that stops in late August, and it is worth treating as an order of magnitude rather than a measurement.
But the deeper problem is not the precision. It is that notional is the wrong quantity.
An S&P 500 index option carries a $100 multiplier. With the index in the 7,500–7,600 area, one contract references about $760,000. Cboe's own trade data showed 25,923,645 contracts of SPX open interest as at 17 September 2026, on volume of 5,131,571 contracts that day. Multiply the open interest out and you get roughly $19.7 trillion of gross notional — in one product line, across every expiration on the board, on a single Thursday.
Nobody has $19.7 trillion at risk in SPX options. The number is arithmetic, not exposure.
| What the number counts | What it actually is |
|---|---|
| Contracts × index level × $100 | A reference amount used to size the contract, not capital committed |
| Far out-of-the-money strikes | Overwhelmingly expire worthless; full notional, near-zero economic value |
| Both legs of a spread | Counted twice, though the two legs largely cancel |
| Calls and puts alike | Counted identically, so the total carries no directional information |
| Covered positions | Written against shares already held; no new exposure created at expiry |
| Hedges | Offset an existing position rather than adding one |
The channel that is real: hedging, not direction
Every flow an expiry generates has two sides. Each closed contract has a counterparty; each hedge unwound was established in both directions. There is no mechanism by which "a lot of contracts expiring" pushes prices one way, and the persistent belief that there is comes from confusing volume with intent.
What an expiry genuinely changes is the quantity of hedging attached to the market.
Dealers who write options do not take the resulting exposure home. They offset it by trading the underlying, and they re-trade it as prices move. Where the dealer community's book requires it to sell into strength and buy into weakness, that continuous re-hedging absorbs movement — it makes realised volatility lower than it would otherwise be, particularly around strikes with very large open interest, which is the origin of the observation that prices sometimes seem to gravitate toward round numbers as an expiry approaches. We walked through the same machinery from the opposite side in the gold dealer-hedging note, where the book was positioned to amplify rather than damp.
When those contracts expire, the hedging attached to them stops. That is a damper being removed, not a force being applied — and it is a conditional, not a prediction, because the whole effect depends on what gets written into October and December in the days afterwards. That positioning does not exist yet. Anyone forecasting next week's tape from this week's expiry is forecasting from a book that has not been opened.
Two rate decisions, both delivered, both largely anticipated
The expiry inherited a week in which the two largest scheduled events resolved without a surprise.
On Wednesday 16 September the Federal Open Market Committee raised the target range for the federal funds rate by a quarter point to 3-3/4 to 4 percent, by a 12–0 vote — the first increase since July 2023. Futures had priced it heavily after the August CPI report, and we covered the decision and the projections that came with it in the three-decisions note. Equities still took it badly on the day, with the Dow falling roughly 600 points, before recovering on Thursday: the Dow closed 316 points higher, up 0.6%, the S&P 500 rose 1.1% and the Nasdaq Composite gained 1.7%, per CNBC's market coverage. Measured across the week to Thursday's close the net was small in two of the three: the Dow down 1.5%, the S&P 500 down 0.3%, the Nasdaq Composite up 0.3%.
Then on Friday morning in Tokyo the Bank of Japan raised its policy rate by 25 basis points to 1.25%, the highest since 1995, on a 7–2 vote with board members Toichiro Asada and Ayano Sato dissenting. Almost 90% of economists surveyed by CNBC had expected the move. Japan's August headline inflation held at 1.9% and core softened to 1.7% from 1.8%.
The reaction is the lesson, and it is the one this site keeps returning to: the yen weakened. It traded at 156.64 after the decision, 0.45% softer, while the ten-year Japanese government bond yield fell 4.9 basis points to 2.947%. A central bank raised rates and both its currency and its long yield went the other way, because neither instrument prices the level — they price the change in the expected path, and a fully anticipated hike delivered with two dissents against it contains no new path. The eight-currency view of that channel sits on the yen page and the dollar page, and it is the same arithmetic we traced through the mortgage market in the Fed-hike spread note.
For the US equity expiry, all of this matters in one narrow way. The two events most capable of forcing a wholesale repositioning of options books both happened before the expiry rather than after it.
The second mechanical order in Friday's close
One more scheduled flow lands in the same closing auction, and it is entirely price-insensitive.
S&P Dow Jones Indices adds Bloom Energy, Everpure and Illumina to the S&P 500 prior to the open on Monday 21 September, replacing Molson Coors Beverage, The Trade Desk and Builders FirstSource. Index funds tracking the S&P 500 must own the new constituents at Monday's opening weights, which in practice means trading them at Friday's close. We measured what that did to the shares on announcement in the September rebalance note — the one genuinely new entrant moved more than three times as much as the two migrations.
Stack the two and Friday's closing auction carries every P.M.-settled option on the board plus a full index reconstitution. Both are obligations rather than opinions. A closing print assembled out of obligation is not a statement about value, which is worth remembering before reading anything into where the week finished.
What would change the picture
The expiry is a known event with known mechanics, so the informative parts are the deviations, not the day itself.
The first is the A.M. settlement value. If the opening auction assembles a settlement number that sits well away from Thursday's close, that gap is real money for holders of standard index options, and it tells you how concentrated the open interest was. The second is the size of the closing auction relative to a normal quarterly close, which separates a rebalance-and-expiry Friday that cleared smoothly from one that did not. The third only becomes visible next week: whether open interest rebuilds in October and December at similar size. If it does, the hedging damper is re-established and the expiry changed nothing structural. If it does not, the market is carrying less of it than before — a condition, not a direction.
What would not change the picture is the trillion-dollar headline itself. It has been growing for years alongside the listed options market, it will be larger again in December, and it will still contain no information about which way anybody is positioned.
Two more Federal Reserve voices close the week: Governor Michelle Bowman, a permanent voting member, and Kansas City Fed President Jeffrey Schmid, who does not vote this year. Their subject is the path, which is the thing that actually prices. For more on the method behind how this site reads events like these, see what pip theory is for.
Educational macro context only — not investment advice.
Frequently asked
What is triple witching and when is it in September 2026?
Why does triple witching cause higher trading volume?
Are S&P 500 options settled at the open or the close on expiry Friday?
How much is actually at risk in a multi-trillion-dollar options expiration?
Does triple witching make the stock market go up or down?
What else is happening on 18 September 2026 besides the expiry?
Related reading
Tokyo CPI Preview (July 2026): Core-Core at 1.9% Meets Brent at $86 — the Last Inflation Print Before the BoJ Decides on 31 July. What It Means for the Yen
Tokyo's July CPI lands 08:30 JST on 31 July, hours before the BoJ decides. Core-core at 1.9% is the number tha…
28 Jul · 12 min Markets
188,000 Barrels Added, 5.5 Million Shut In: The OPEC+ Meeting of 6 September 2026 — and Why the Quota Stopped Setting the Oil Price
OPEC+ meets at 11:00 GMT on 6 September to set October quotas. With 5.5 mb/d shut in and the 2027 capacity aud…
3 Sep · 13 min1.25% and a Weaker Yen (18 September 2026): The Bank of Japan Hiked to a 31-Year High, and the Two Dissents Did the Talking
The BoJ hiked to 1.25% on 18 September and the yen fell, JGB yields slipped and the Nikkei rose 1.5%. Why a 7–…
14 Sep · 26 min