
2.50% Hold Expected, 64 of 73 See December (ECB Decision Preview, 29 October 2026): What to Expect and What It Means for the Euro
The ECB decides 29 October at 13:15 GMT; 70 of 73 economists expect a hold at 2.50% and 64 see a December hike. The scenario map for the euro.
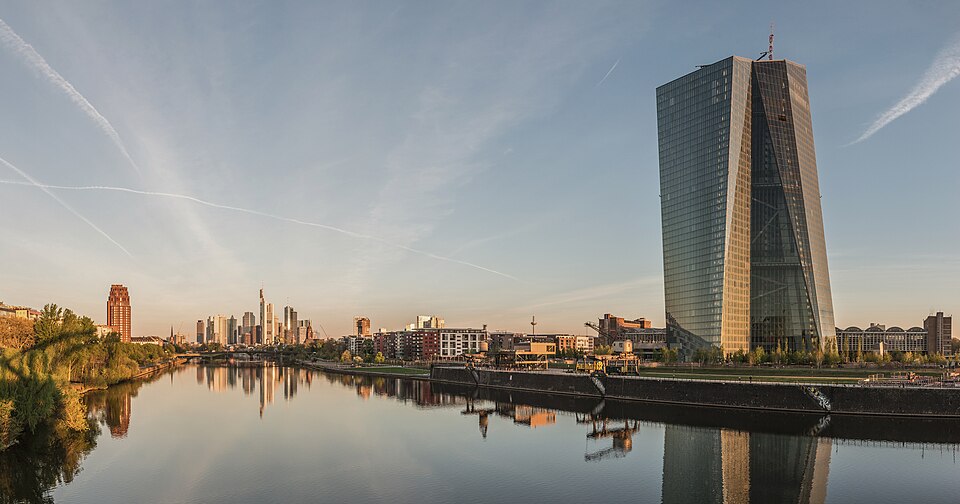
2.50% Hold Expected, 64 of 73 See December (ECB Decision Preview, 29 October 2026): What to Expect and What It Means for the Euro
The European Central Bank announces its decision on Thursday 29 October at 13:15 GMT, and 70 of 73 economists polled by Reuters expect it to hold the deposit rate at 2.50%. The rate is not the question. With euro area inflation at 3.8% and 64 of the same 73 economists expecting another hike in December, the euro will trade on whether the statement and Lagarde's press conference protect that December move or chip away at it — and it goes in fixed at 1.1150 against the dollar, its weakest since May 2025.
- When. Thursday 29 October, statement at 14:15 CET (13:15 GMT, 09:15 New York); press conference at 14:45 CET. No new projections until December.
- The rate. A hold at 2.50% on the deposit facility, after hikes in June and September. 70 of 73 economists in the Reuters poll expect it.
- The real question. December: 64 of 73 economists expect a 25bp hike, and markets price nearly three more by the end of 2027.
- The data. September inflation 3.8%, energy 18.9%, core 2.5%, services 3.2% — energy is the shock, core is the test.
- The euro. Trades on the December path against the Fed's, decided the night before, with a fiscal premium from France and Spain on top. See where EUR scores across all five factors on the live meter.
When the decision lands and what comes with it
The Governing Council's monetary policy statement is published at 14:15 CET on Thursday 29 October. Europe changed its clocks on 25 October and the US does not change until 1 November, so for one week the gap is an hour shorter than usual: that is 13:15 GMT and 09:15 in New York. Christine Lagarde's press conference follows half an hour later.
October is not a projection month. The ECB's staff publish new growth and inflation forecasts four times a year, and the next set comes in December. That shapes what this meeting can and cannot say: the Council has no new forecast to point to, so any change in its message has to come through the wording of the statement and through Lagarde's answers.
It is also the middle decision of three in three days. The Federal Reserve announces on Wednesday 28 October, where a Reuters poll found 94 of 100 economists expecting a hold and futures priced roughly a 71% chance of a December hike (see our Fed preview). The Bank of Japan follows on Friday (our BoJ preview). All three are leaning towards tightening by year-end, which matters for the euro in a way the ECB decision alone does not capture.
Where rates stand going in
The September decision, covered in our September ECB analysis, raised all three key rates by 25 basis points from 16 September:
| Key ECB rate | From 17 June 2026 | From 16 September 2026 | Expected after 29 October |
|---|---|---|---|
| Deposit facility | 2.25% | 2.50% | 2.50% |
| Main refinancing operations | 2.40% | 2.65% | 2.65% |
| Marginal lending facility | 2.65% | 2.90% | 2.90% |
The September statement kept the phrase that matters most for this week: the Council is not pre-committing to a particular rate path and decides meeting by meeting. Its staff projections put headline inflation at 3.0% in 2026, 2.5% in 2027 and 2.1% in 2028 — above target in the final year of the horizon for the first time in the cycle. That forecast, not the hike itself, was the September news.
What is expected: a hold, and a December question
The ECB's October decision is about as settled as a central bank decision gets. In the Reuters poll taken between 5 and 8 October, all but three of 73 economists expected the deposit rate to stay at 2.50%, and money markets attached only a basis point or two of tightening to this meeting.
The shift is in December. The same poll found 64 of 73 economists expecting a quarter-point hike at the December meeting, a reversal from the previous month's survey, when more than 90% expected rates to stay on hold. On where the cycle ends:
- 40 of 70 respondents saw the deposit rate peaking at 2.75% — one more hike.
- 24 expected 3.00%, up from just two a month earlier.
- Markets price nearly three further hikes by the end of 2027.
The poll also raised its inflation path: an average of 3.7% in the fourth quarter, 3.0% for 2026 and 2.6% for 2027, up from 2.9% and 2.3%. Lagarde has described the approach as a "measured response," Reuters reported, and the accounts of the September meeting showed all policymakers agreed inflation risks were skewed to the upside.
The doubts in the poll were about how far, not whether. "I do not have a very strong conviction they go to 2.75% and stay there," Jens Eisenschmidt of Morgan Stanley told Reuters, adding that his forecast was "predicated on oil prices not increasing more and activity not accelerating further from here."
The data the Council takes into the room
The October flash inflation estimate is not due until 4 November, so the latest full reading is September's, confirmed by Eurostat on 16 October:
| Euro area HICP, annual rate | August 2026 | September 2026 | Contribution in September |
|---|---|---|---|
| Headline | 3.2% | 3.8% | — |
| Energy | 14.3% | 18.9% | 1.71pp |
| Services | 3.0% | 3.2% | 1.52pp |
| Non-energy industrial goods | 1.2% | 1.1% | 0.29pp |
| Food, alcohol & tobacco | 1.1% | 1.3% | 0.25pp |
| Core (ex energy, food, alcohol & tobacco) | 2.4% | 2.5% | — |
The shape of that table is the whole debate. Energy, at under a tenth of the basket, supplied 1.71 of the 3.8 percentage points. Strip it out, along with food, alcohol and tobacco, and inflation is 2.5% — above target, but up only a tenth on the month. Goods excluding energy actually slowed. Reuters' poll write-up noted there was little evidence yet that higher energy prices from the war with Iran were spreading to other consumer prices.
Activity is the counterweight. Euro area surveys for October weakened, with France's in contraction, and the ECB's own bank lending survey reported a further tightening of credit standards. Those are the arguments for patience, and they are the reason a December hike is a strong consensus rather than a certainty. The first estimate of third-quarter euro area GDP lands on Friday 30 October, the day after the decision.
The scenario map
| Scenario | What the ECB delivers | What it does to December | Euro channel |
|---|---|---|---|
| Hawkish hold (consensus) | Hold at 2.50%; upside inflation risks stressed; signs of pass-through acknowledged; no pre-commitment but no pushback on December | Protects it — little left to add if it is already the majority view | Modest. The rate factor already scores a December hike, so the euro needs the relative path to improve against the Fed, not just be confirmed |
| Patient hold | Hold, with emphasis on weaker surveys, tighter lending, higher bond yields "doing some of the work," and no wage response yet | Pushes the next hike towards early 2027 or trims the terminal rate back to 2.75% | Euro-negative at the margin: the expected rate gap with the dollar stays wider for longer, on top of an existing fiscal discount |
| Surprise hike to 2.75% | A back-to-back move, which the poll did not rule out entirely | Pulls the cycle forward and raises the odds of a 3.00% peak | The largest repricing — the forward path shifts, not one meeting, though it would also tighten conditions for the most indebted governments |
Why the euro trades on the relative path — and on France
The euro's reference rate against the dollar was set at 1.1150 on 27 October, according to the ECB's daily fixing — below the 1.1204 low covered in our analysis of the euro's October slide, and the weakest since May 2025. That decline happened while the ECB was hiking, which is the point: a rate increase that is matched or exceeded elsewhere does nothing for a currency through the rate channel.
Two things sit on top of the rate gap. The first is the Fed. If Wednesday's statement firms up a December Fed hike, an ECB December hike merely keeps pace; if the Fed sounds less sure, the same ECB move narrows the gap. That is why the euro's reaction on Thursday depends partly on what happened in Washington twelve hours earlier.
The second is fiscal. French government bond spreads over Germany have widened, and Spain holds a snap general election on 29 November. That is a risk premium, not a rate story: investors demand extra compensation for holding the assets of the weakest borrowers in the currency union, and some of that shows up in the currency. A hawkish ECB does not remove it. If anything, higher policy rates raise the cost of servicing the largest debt piles, which is why questions on France and the ECB's crisis backstop are likely in the press conference. The answer the market wants is that the backstop exists; the ECB will not want to pre-judge whether any country qualifies.
There is a leadership thread as well. Lagarde's term runs to the end of October 2027, and she told Les Échos in July that leaving early was "possible" ahead of France's 2027 presidential election (covered in our Lagarde analysis). Several Executive Board seats are due to turn over in 2027. Succession affects the currency only through the expected policy path, so it matters if questions on it change how the market reads the reaction function — not because of who sits in the chair.
What would change the picture
- The Fed on Wednesday. A firmer December signal from Washington raises the bar for the euro to gain from a hawkish ECB; a softer one lowers it.
- Energy prices. Eisenschmidt's forecast, like most, assumes oil does not rise further. Another leg higher in oil or gas raises the near-term inflation path but also deepens the terms-of-trade loss for a large energy importer — which is why higher energy prices have coincided with a weaker euro rather than a stronger one.
- Third-quarter GDP on Friday. A weak first estimate would support the "patient" reading regardless of what Lagarde says on Thursday.
- The 4 November flash. October inflation lands six weeks before the December decision. A core reading that stays near 2.5% while energy remains high keeps the debate where it is; a jump in services would settle it.
- France's spread. A widening that the ECB is seen as reluctant to address adds to the fiscal discount on the currency independently of the rate path.
For background on how the currency responds to these channels, see the euro page and the dollar page, and read more about how the site works on the about page.
Educational macro context only — not investment advice.
Frequently asked
When is the ECB's October 2026 decision?
Will the ECB raise rates in October 2026?
What is euro area inflation right now?
Why would the ECB hike in December but not in October?
How could the ECB decision affect the euro?
Related reading
 Currencies
1.25% Hold Expected, ~80% Priced for December (BoJ Decision Preview, 30 October 2026): What to Expect From the Outlook Report and What It Means for the Yen
The BoJ decides 30 October and is expected to hold at 1.25% while declaring its 2% goal roughly met. Swaps pri…
27 Oct · 10 min Currencies
94 of 100 Expect a Hold, 71% Price a December Hike (Fed Decision Preview, 28 October 2026): What to Expect and What It Means for the Dollar
The Fed decides 28 October at 2pm ET. 94 of 100 economists expect a hold at 3.75–4.00% and futures price ~71% …
26 Oct · 9 min3.2% Heading for 3.5–3.7% (Eurozone Flash CPI Preview, 2 October 2026): What to Expect and What It Means for the Euro
Eurozone September flash CPI lands 2 October at 09:00 UTC; forecasts run 3.5–3.7% from 3.2%. Core and services…
29 Sep · 10 min