
91% of Refining Against 13m Tonnes of Soybeans (Xi–Trump Summit Preview, September 2026): What Each Side Owes Before 10 November
Xi meets Trump at the White House on 24 September. China refines 91% of the world's rare earths and the truce clocks run out on 10 November. The mechanism.
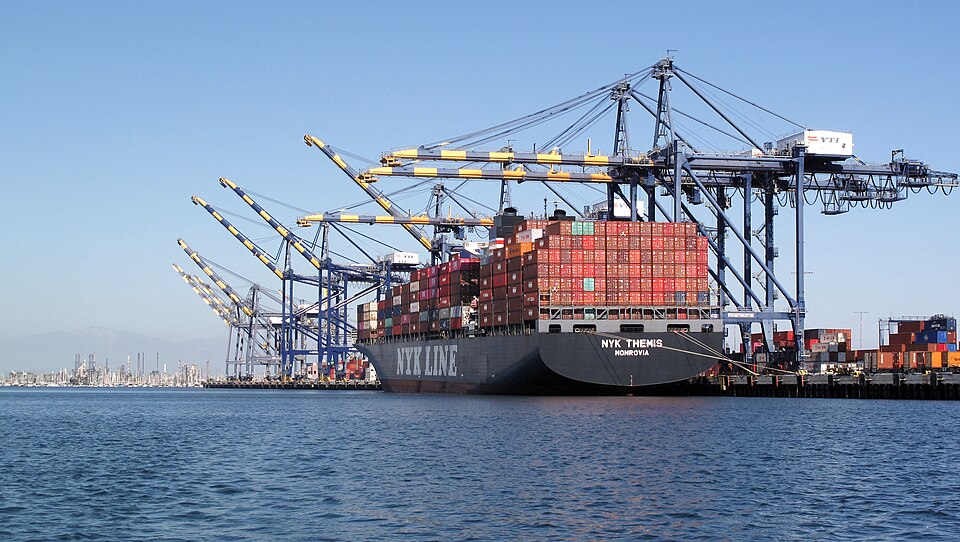
91% of Refining Against 13m Tonnes of Soybeans (Xi–Trump Summit Preview, September 2026): What Each Side Owes Before 10 November
Xi Jinping arrives at the White House on 24 September 2026 for his first visit since 2015, and the American side has told anyone who asked what the meeting is for. Bloomberg reported US Trade Representative Jamieson Greer describing it as "a moment for stock-taking, confirming the relationship, making sure China is complying with what it has agreed to do." The awkward part is what is being audited. The truce struck in Busan in October 2025 traded American tariff relief for Chinese concessions on rare earths, agriculture and export controls — and on 20 February 2026 the Supreme Court abolished the tariff authority the American half rested on. China's obligations still run to a 10 November clock. America's were overtaken by its own courts seven months ago.
- The date is set and the groundwork is done. Xi is scheduled in Washington on 24 September. On Sunday 20 September Greer joined Treasury Secretary Scott Bessent in New York to meet Vice Premier He Lifeng, per a USTR statement dated 18 September.
- It is framed as an audit, not a negotiation. Greer's stated aim is "monitoring the implementation of recent commitments, optimizing trade in non-sensitive goods, and improving market access."
- Almost every clock in the truce runs out on 10 November 2026 — the reciprocal-tariff suspension, the Section 301 exclusions, the affiliates rule, the shipbuilding actions, and China's suspension of its 9 October 2025 rare-earth controls.
- The American half was voided in February. Learning Resources, Inc. v. Trump held 6–3 that IEEPA does not authorise tariffs, so the relief Washington had promised to suspend was abolished outright — by a court, for nothing in return.
- The leverage is not symmetrical. The IEA puts China at 91% of refined rare earth output and roughly 94% of permanent magnet production. That is an administrative lever Beijing can adjust; a court ruling is not something Washington can trade back.
- The yuan is at its strongest of 2026 — 6.6976 per dollar on 18 September against 7.0010 at end-2025 — and it got there by monthly grind, not by a summit trade.
- See how the rate, growth, risk and commodity factors are scoring the eight majors right now on the live meter.
What the 24 September meeting is actually for
Start with what has been said on the record, because it is unusually explicit. USTR announced on 18 September that Greer would join Bessent in New York on Sunday 20 September to meet Vice Premier He Lifeng "ahead of the U.S.-China Summit in Washington, DC." Greer's accompanying line described the American programme as pursuing balanced trade "by monitoring the implementation of recent commitments, optimizing trade in non-sensitive goods, and improving market access for American farmers, manufacturers, and workers."
Every clause there is about administering something that already exists. Bloomberg had reported the same framing in July, quoting Greer calling the summit a moment for stock-taking. Expectations among China analysts have been set accordingly: Craig Singleton of the Foundation for Defense of Democracies told CNBC it was "a low-expectations summit focused largely on managing the stalemate rather than resolving it," adding that the relationship "increasingly produces transactions without trust and stability without settlement."
For a reader deciding how much attention to pay, that is the useful signal. A summit convened to verify compliance has a much narrower distribution of outcomes than one convened to strike a deal, and the market consequence of a narrow distribution is that the event itself is usually worth less than the calendar around it.
The deal being audited lost its American half in February
The Busan package was specific. The White House fact sheet of 1 November 2025 recorded that the United States would remove ten percentage points from the fentanyl-related tariff rate effective 10 November 2025 and "maintain its suspension of heightened reciprocal tariffs on Chinese imports until November 10, 2026," with a 10% reciprocal tariff running during the suspension. China, in exchange, would suspend the rare-earth export controls announced on 9 October 2025, issue general licences covering rare earths, gallium, germanium, antimony and graphite, suspend retaliatory tariffs and countermeasures taken since March 2025, and buy at least 25 million tonnes of US soybeans in each of 2026, 2027 and 2028.
Then, on 20 February 2026, the Supreme Court held 6–3 in Learning Resources, Inc. v. Trump that IEEPA "does not authorize the President to impose tariffs." Both the reciprocal tariffs and the fentanyl measures had been imposed under that statute. Both fell, and the money collected under them had to come back — a refund whose fiscal footprint we traced in the gap between gross and net customs receipts.
What replaced them was not nothing. A temporary Section 122 balance-of-payments surcharge of 10% ran from 24 February for its statutory maximum of 150 days, and when it lapsed on 24 July it was replaced the same morning by permanent Section 301 duties of 10% or 12.5% across the top 60 trading partners — the handover we covered at the time. Section 232 duties on steel, aluminium and copper were never at issue. Neither were the older Section 301 China lists.
The asymmetry, in one table
Set out what each side is still carrying into the meeting and the imbalance becomes plain.
| Obligation from the November 2025 truce | Status as of 20 September 2026 |
|---|---|
| US: suspend heightened reciprocal tariffs to 10 Nov 2026 | Moot — authority voided 20 Feb 2026 |
| US: cut fentanyl tariff by 10 percentage points | Moot — same ruling, duties refunded |
| US: extend Section 301 exclusions to 10 Nov 2026 | Live, expires 10 Nov 2026 |
| US: suspend affiliates rule, one year from 10 Nov 2025 | Live, expires 10 Nov 2026 |
| US: suspend Section 301 shipbuilding actions, one year | Live, expires 10 Nov 2026 |
| China: suspend 9 Oct 2025 rare-earth controls, one year | Live, expires 10 Nov 2026 |
| China: 25m tonnes of soybeans per calendar year, minimum | Reported near 13m tonnes for the season |
| China: general licences on rare earths, gallium, germanium | Live; ten US firms blacklisted 22 Jun 2026 |
Read the first two rows against the rest. The two largest American concessions were delivered in full, permanently, and not by the administration that promised them. Everything China conceded was a discretionary administrative act with a renewal date attached. That does not make either side's conduct a grievance — it is simply the structure of what is on the table, and it explains why the American framing is compliance-checking rather than deal-making. There is less left to offer than there was in Busan.
The chokepoint is downstream, and it constrains more than trade policy
The reason China's side of the ledger still carries weight is concentration, and the numbers are not close. The IEA puts China at 91% of global refined rare earth output and about 94% of sintered permanent magnet production in 2024, against roughly 60% of mined production of magnet rare earths. The bottleneck is not the mine. It is separation, refining and magnet-making — the stages that take years and specialised chemistry to replicate, and where the agency expects capacity outside China to cover only about a quarter of refining demand and under a fifth of magnet demand by 2035.
That concentration has already been used twice in 2026. On 22 June, as Al Jazeera reported, China's Commerce Ministry added ten US entities to its export control list with immediate effect, including the rare-earth miner MP Materials and the magnet maker USA Rare Earth, alongside aerospace, drone, radar and shipbuilding firms; the ministry described the step as a response to the United States expanding its own list of Chinese military-linked entities. The direct commercial bite was limited, since both companies had already largely severed Chinese supply. The signal was not limited at all: a suspension is only a suspension, and the list is still being edited.
It also reaches policy that has nothing to do with trade. Treasury announced a secondary-sanctions campaign against Iran's trading partners on 24 August, and China is by far Iran's largest oil customer. Scott Kennedy of the Center for Strategic and International Studies told CNBC the United States "is finding itself increasingly between multiple rocks and multiple hard places" on the two files at once. The mechanism is straightforward: an enforcement action severe enough to bite Chinese buyers of Iranian crude invites a response in the one supply chain where American substitution is measured in years. That is a genuine constraint on how hard the sanctions can be pressed, and it is visible in the fact that no country has yet been named or dated — the same open calendar that kept the risk premium out of the barrel in August.
The agricultural ledger, and which clock it is kept on
The May 2026 Beijing summit produced the commitments this meeting is meant to check, and USTR published them in Greer's own words on 18 May: US meat plants that China had deregistered were being re-registered, biotechnology traits were to be reviewed, non-tariff barriers on beef and poultry were being reduced, and China had agreed to 200 Boeing aircraft — the first major Chinese order in almost a decade. A US-China Board of Trade was chartered to handle, in Greer's phrase, "trade in non-sensitive goods". He also said the US trade deficit with China had fallen 33%, or $130bn, over the preceding year.
On soybeans, Bloomberg reported on 14 September that purchases for the current season had reached close to 13 million tonnes, more than half the 25-million-tonne annual target, with state traders booking at least a million tonnes in the preceding week.
Here the careful reader should slow down. The White House commitment is written in calendar years — "in each of 2026, 2027, and 2028". USDA reports soybean export sales on a marketing year that runs 1 September to 31 August. Those are different windows, and coverage of "the current season" does not consistently say which one it means. A commitment measured in one unit and audited in another can be reported as comfortably on track or meaningfully behind without anyone misstating a figure. That is not a scandal; it is a drafting choice with consequences, and it is the sort of thing a stock-taking meeting exists to pin down.
What the market has priced, and what it has not
Very little of this is in the price, and the yuan shows why. On European Central Bank reference rates the dollar bought 7.0010 yuan at the end of 2025 and 6.6976 on 18 September 2026 — a 4.3% fall in the dollar leg, and the strongest yuan of the year.
| Month-end, USD/CNY | Rate |
|---|---|
| 31 Dec 2025 | 7.0010 |
| 27 Feb 2026 | 6.8582 |
| 30 Apr 2026 | 6.8287 |
| 30 Jun 2026 | 6.7855 |
| 31 Aug 2026 | 6.7197 |
| 18 Sep 2026 | 6.6976 |
The shape matters more than the level. This is a monthly grind of roughly a third of a percent, not a repricing around the 23 July announcement of the summit date or around February's ruling. A managed currency moving in a straight line is telling you about policy preference, not about event risk — and it means there is no summit premium in the yuan to be given back if the meeting disappoints.
The eight currencies the meter scores do not include the yuan, and the honest read-across is narrower than it is often made to sound. The Australian dollar is the cleanest China proxy among the majors, because Chinese industrial demand reaches it through the commodity factor and through growth expectations simultaneously — the full mechanism is here, and the live factor read sits on the AUD currency page. For the dollar itself the summit is a second-order input; the USD page is still being driven by rates.
What would change the picture
Three things, in descending order of how cleanly they would transmit.
The 10 November renewals. Five separate suspensions lapse on one date, and only one of them — China's rare-earth controls — has a direct, fast channel into industrial output. Whether that suspension is renewed, extended in a different form, or allowed to expire is the single most consequential question attached to this summit, and it does not have to be answered on 24 September.
Whether the meeting happens as scheduled. The Washington Post reported in May that the United States paused a $14bn Taiwan arms package after the Beijing summit. In September, Kyodo News reported, citing diplomatic sources, that Beijing had warned it would cancel the Washington meeting if that package were approved beforehand; a senior US official has since disputed that account to another outlet. Both the report and the denial are unconfirmed, which is exactly why neither is priced. A cancelled state visit would be a genuine risk event; a contested news report about a possible cancellation is not one.
The Iran file. Bessent has said AI will be on the agenda and that no one is above the reach of US sanctions. If the secondary-sanctions campaign acquires a named Chinese counterparty and a date, the minerals channel becomes the retaliation channel, and the two files stop being separable.
The framing that survives all of it is the one the American negotiator supplied himself. This is a stock-taking exercise between two governments whose last agreement was partly dissolved by a court, with most of its remaining terms expiring seven weeks later. A reader who understands that will not be surprised by a thin communiqué, and will know which November dates to put in the calendar regardless of what is said on the day.
Educational macro context only — not investment advice.
Frequently asked
When is the Trump–Xi summit and what is on the agenda?
What happens on 10 November 2026?
Why does the Supreme Court ruling matter for the China trade deal?
Has China met its soybean purchase commitment?
How does any of this reach markets a reader can actually trade?
Related reading
Core CPI 0.3% Against 0.2% Expected (11 September 2026): August Inflation Firmed on the Month and Eased on the Year — Four Days Before the Fed Decides
August core CPI rose 0.29% against a 0.2% consensus while the annual rate fell to 2.4%. The split print, the j…
9 Sep · 12 min Markets
$6.97m a Day From 1 October (September 2026): The Paramount–Warner Bros Deal Spread Is a Court Calendar With a Price on It
Paramount owes WBD holders $6.97m a day from 1 October. With WBD at $28.04 against a $31.00 cash deal, here is…
12 Sep · 10 minTokyo CPI Preview (July 2026): Core-Core at 1.9% Meets Brent at $86 — the Last Inflation Print Before the BoJ Decides on 31 July. What It Means for the Yen
Tokyo's July CPI lands 08:30 JST on 31 July, hours before the BoJ decides. Core-core at 1.9% is the number tha…
28 Jul · 12 min